Biohazard cleanup after a death, accident, or traumatic event can cost thousands of dollars — and most tenants only discover the limits of their policy after filing a claim. Understanding how renters insurance biohazard cleanup coverage actually works in 2026 is genuinely useful before a crisis hits and critically important if one already has.
The fundamental thing to understand before anything else: renters insurance does not cover the building. It covers your personal property (contents) and your personal liability. That distinction determines who files which claim — and getting it wrong from the start can cost you weeks of delays and thousands of dollars in disputed costs.
Does Renters Insurance Cover Biohazard Cleanup? The Core Rule
Personal Property vs. Structural Damage: Who Pays for What?
This is the baseline rule that most articles on this topic bury or skip entirely. A standard renters policy has two relevant components for biohazard situations: Contents Coverage, which applies to the tenant’s personal belongings, and Personal Liability Coverage, which applies when a third party is injured or their property is damaged due to the tenant’s negligence. What renters insurance never covers is the building’s structure — walls, subflooring, built-in HVAC systems, landlord-owned appliances. That’s the landlord’s policy.
This matters practically because biohazard contamination doesn’t respect those lines. Blood that saturates a tenant’s mattress is a contents claim under the renter’s policy. That same blood seeping through the floor into the subfloor below is a structural claim under the landlord’s dwelling insurance. When an adjuster receives a claim, they’re making exactly this distinction — and a single invoice that bundles both without separating them often triggers a dispute.
Here’s how ownership maps to policy responsibility:
| Contaminated Item / Area | Primary Responsible Policy | Why This Policy Applies |
|---|---|---|
| Tenant’s furniture, clothing, bedding | Renters insurance (Personal Property/Contents) | The tenant owns these items; remediation or replacement falls under standard peril clauses |
| Drywall, subflooring, landlord appliances | Landlord’s property insurance (Dwelling Policy) | Structural elements of the building — the property owner is legally required to maintain habitability |
| Third-party guest injury or cleanup | Renters insurance (Liability portion) | Applies if tenant’s negligence directly caused harm or contamination to a guest inside the unit |
| Apartment hallways / shared HVAC units | Commercial landlord liability | Common areas fall strictly under building management’s operational umbrella |
When Will a Tenant’s Policy Approve a Trauma Cleanup Claim?
The “Sudden and Accidental” Rule Explained
Coverage approval nearly always hinges on one phrase: “sudden and accidental.” Insurance companies use this standard to separate insurable events — a discrete, unexpected incident — from gradual contamination that built up over time, which falls under wear and tear or neglect rather than a covered peril. An accidental death in a rental unit that occurred yesterday is a sudden event. An unattended death undiscovered for several weeks, where decomposition has been spreading throughout the structure, is one where insurers will scrutinize the timeline of discovery heavily before approving anything.
Covered Perils: When Violent Crime or Fatal Accidents Trigger Coverage
Accidental deaths, sudden medical emergencies, and violent crimes committed by a third party are the most consistently covered triggers for tenant policy indemnity. When a forced-entry crime or violent incident occurs in the unit, the contamination that results is typically treated as covered property damage — the tenant is a victim, not the responsible party, and the “sudden and accidental” standard is clearly met. Coverage is more likely when the event is unexpected, the damage is direct, and the tenant reported the incident promptly.
Why Biohazard Cleanup Claims Get Denied by Insurers
The Gradual Contamination Trap: The Timeline Problem in Unattended Deaths
The most common denial scenario in biohazard claims is the unattended death where discovery was delayed. The longer the body went undiscovered, the more likely an insurer will argue that contamination spread gradually rather than resulting from a single sudden event — even though the death itself was sudden. Framing the claim correctly matters enormously here: the death was sudden and accidental; the discovery was delayed. These are different facts, and a well-documented timeline that establishes the date of death versus the date of discovery can be the difference between approval and denial.
The “Illegal Activity” and Intentional Acts Policy Exclusions
Two exclusion clauses catch tenants off guard more than any others. The illegal activity exclusion means that if biohazard contamination resulted from drug manufacturing, trafficking, or other criminal activity by the insured, the claim will almost certainly be denied regardless of the peril language. The intentional acts exclusion applies when the policyholder caused the contamination deliberately. Note that suicide cases sit in a grey area: most standard renters policies do cover them under accidental or sudden peril clauses, but a small number include explicit exclusions for self-inflicted damage within the first two years of the policy — check your declarations page before assuming coverage.
How Much Does Biohazard Remediation Cost in 2026?
| Cleanup Type | Typical Cost Range |
|---|---|
| Small blood cleanup | $1,000 – $3,000 |
| Crime scene cleanup | $3,000 – $15,000+ |
| Unattended death cleanup | $5,000 – $25,000+ |
| Severe contamination cases | $25,000+ |
Why You Cannot DIY a Biological Decontamination Event (OSHA Standards)
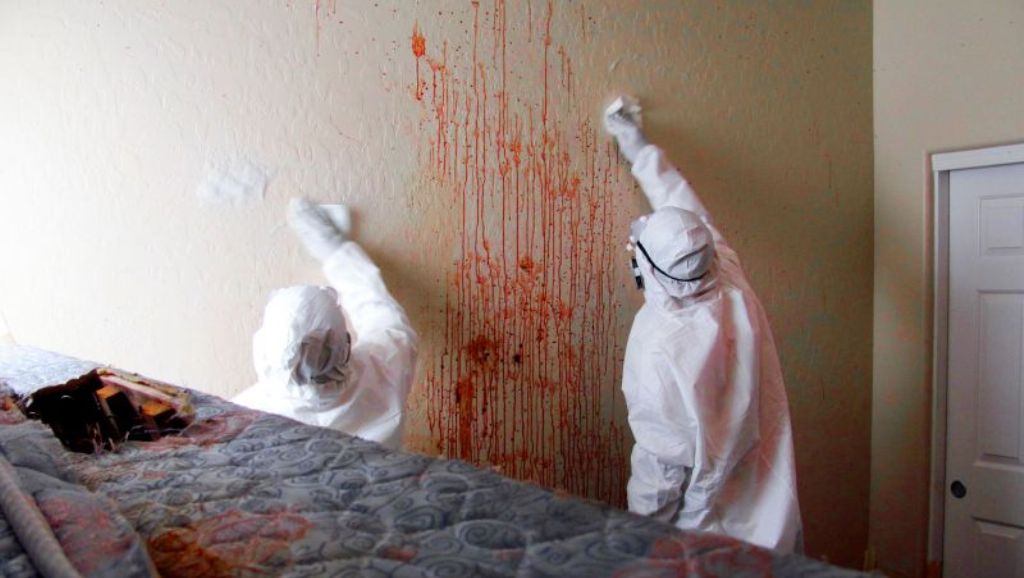
The cost of professional remediation reflects a regulatory reality, not just market pricing. Under the OSHA Bloodborne Pathogens Standard (29 CFR 1910.1030), any company sending workers into a contaminated environment must maintain a documented Exposure Control Plan, provide Hepatitis B vaccinations, and equip technicians with appropriate Level C personal protective equipment.
A general cleaning service operating without these protocols isn’t just cutting corners — it’s creating OSHA violations. Insurers know this, which is why DIY cleanup attempts or non-certified cleaning invoices are a common reason claims are partially or fully denied: the adjuster has no way to validate that the space is actually safe.
Before you contact a cleaning company, read our guide on what to do before hiring a biohazard cleanup company — the vetting steps there can also protect your insurance claim.
Loss of Use: Filing an Additional Living Expenses Claim After a Biohazard Event
If a biohazard incident makes your apartment temporarily uninhabitable, your renters insurance may provide Loss of Use or Additional Living Expenses (ALE) coverage. This can help reimburse costs such as temporary accommodation and extra living expenses while the property is being restored.
The first step is obtaining written proof that the unit is unsafe to occupy. This may come from an IICRC-certified remediation contractor, your landlord, property manager, or local authorities. Once documented, contact your insurance adjuster and request that an ALE claim be opened, as it is separate from any property damage or contents claim.
ALE coverage typically reimburses additional expenses caused by displacement, including hotel stays, increased meal costs, storage, and laundry. Keep detailed records and save all receipts from the day you leave the property.
Submit expenses regularly rather than waiting until the end of the claim period. Maintaining a clear log of normal living costs versus emergency expenses can help speed up reimbursement and reduce disputes.
Most policies limit ALE coverage by either a maximum dollar amount or the time reasonably required to restore the property. Request a written remediation timeline at the start of the project to help establish the covered period and support your claim.
Alternative Funding: What to Do If Your Claim Is Denied
How State Crime Victim Compensation Funds Cover Cleanups
A denied or underpaid renters insurance claim is not the end of the road if the biohazard event resulted from a violent crime. Every U.S. state operates a Crime Victims Compensation (CVC) program, and biohazard remediation is an explicitly covered eligible expense under the federal Victims of Crime Act (VOCA) that funds them.
These programs operate as a payer of last resort — you must exhaust applicable insurance first — but they exist precisely for situations where insurance falls short. Reimbursement caps vary significantly by state: Illinois’s program covers up to $45,000 for crimes after August 2022; New York expanded crime scene cleanup reimbursement in late 2025 to cover anyone affected regardless of whether they lived at the scene; Wisconsin caps cleanup compensation at $1,000. Contact your state Attorney General’s office to confirm your state’s specific limits and application requirements. The National Association of Crime Victims Compensation Boards maintains a directory of every state program with direct contact information.
When to Hold Your Landlord Financially Liable for Remediation
If the biohazard event involves contamination that has spread to structural elements — subflooring, walls, shared HVAC systems — the landlord’s dwelling policy is the appropriate claim vehicle, not your renters policy. Landlords have a legal obligation to maintain habitable conditions under the implied warranty of habitability doctrine recognised in virtually every U.S. state. If your landlord refuses to remediate structural contamination after a documented biohazard event, that refusal can constitute a breach of this warranty, giving you grounds to withhold rent, break the lease without penalty, or pursue a civil claim depending on your state’s tenant protection statutes. Document all written communications with the landlord from the moment you report the incident.
Documentation Checklist: What Adjusters Actually Need
A disorganised claim is a delayed or denied claim. For any renters insurance biohazard cleanup submission, adjusters typically require: a police report or incident number for violent crime claims; pre-remediation photographs of both room entrances and specific contaminated surfaces; an IICRC-certified contractor invoice with Xactimate line-item billing rather than a flat-sum quote; medical or coroner documentation establishing the date and nature of the incident; a written uninhabitability statement from the remediation contractor for any ALE claim; a waste manifest confirming legally compliant biohazardous disposal; and receipts for all ALE expenses with a normal-cost baseline documented separately.
Submit documentation as it becomes available — don’t wait until the job is complete to send everything at once. Adjusters process rolling submissions more efficiently than single large packets, and early submission creates a documented timeline that works in your favour if the claim is disputed later.
The Bottom Line
Renters insurance biohazard cleanup coverage can provide meaningful financial protection after a traumatic event, but it rarely operates automatically. Whether a claim succeeds depends on the cause of the incident, whether it qualifies as sudden and accidental under your specific policy language, how quickly you reported it, whether a certified contractor performed the work, and how thoroughly you documented every step. Understanding the personal property versus structural split before you file determines which policy you’re activating — and getting that right from hour one is the single most consequential thing a tenant can do.
If you need a verified, IICRC-certified specialist in your area who works directly with insurance adjusters, submit a request at BioRecoveryPro and we’ll match you within minutes, 24/7.
Pingback: Do You Legally Have to Tell Buyers Someone Died in Your House? - BioRecoveryPro
Pingback: Found Your Pet Dead and Decomposed? Here's Exactly What to Do - BioRecoveryPro