Here’s something nobody tells you in the immediate aftermath of a traumatic event at your property: the decisions you make in the first few minutes after the scene is released often matter more to your insurance payout than anything the remediation crew does afterward. Biohazard insurance claim documentation isn’t something you can fix retroactively once cleanup has started, and that’s exactly why so many homeowners end up fighting an adjuster over a claim that should have been approved without argument.
If you’re standing at the threshold of a property right now trying to figure out what to do, this guide walks through exactly what to document, in what order, and why skipping any of it hands your adjuster an easy reason to reduce what they pay.
Why Cleaning First Is the Single Biggest Mistake You Can Make
The instinct to clean up, to make the space livable again, to just be done with it — that instinct is completely human and completely understandable. It’s also the single fastest way to lose money on your claim.
Once a remediation crew begins work, the original condition of the property is gone. There’s no way to reconstruct exactly how far contamination spread, how deeply it penetrated flooring, or what the true scope of damage looked like before anyone touched it. Adjusters know this, and they evaluate claims accordingly: a claim supported by pre-remediation photographs and an independent visual inspection gets treated very differently from one where the homeowner’s word is the only evidence of what the property looked like beforehand.
Before anyone starts cleaning, before you move a single item, get comprehensive photographic evidence of the entire affected area. Wide shots of every room showing the full extent of visible damage. Close-up shots of specific contaminated surfaces. Photos of anything that shows fluid pooling, staining patterns, or visible penetration into flooring or walls. This documentation exists independently of whatever your remediation contractor photographs, and having your own record protects you if a dispute arises later about what the adjuster actually saw versus what genuinely happened.
How to File a Claim for Trauma Scene Cleanup: The Right Order of Operations
Getting the sequence right here matters as much as the individual steps themselves.
Contact your insurance company before remediation begins, not after. Ask specifically for an adjuster, not a general customer service representative — adjusters are the ones with the authority and technical knowledge to open a proper claim file and advise you on documentation requirements specific to your policy. Get a claim number in writing before any cleanup work starts.
Document the scene thoroughly, as described above, before a single item is touched. This isn’t optional even if you’re in a hurry to move forward emotionally — it’s the foundation every other part of your claim rests on.
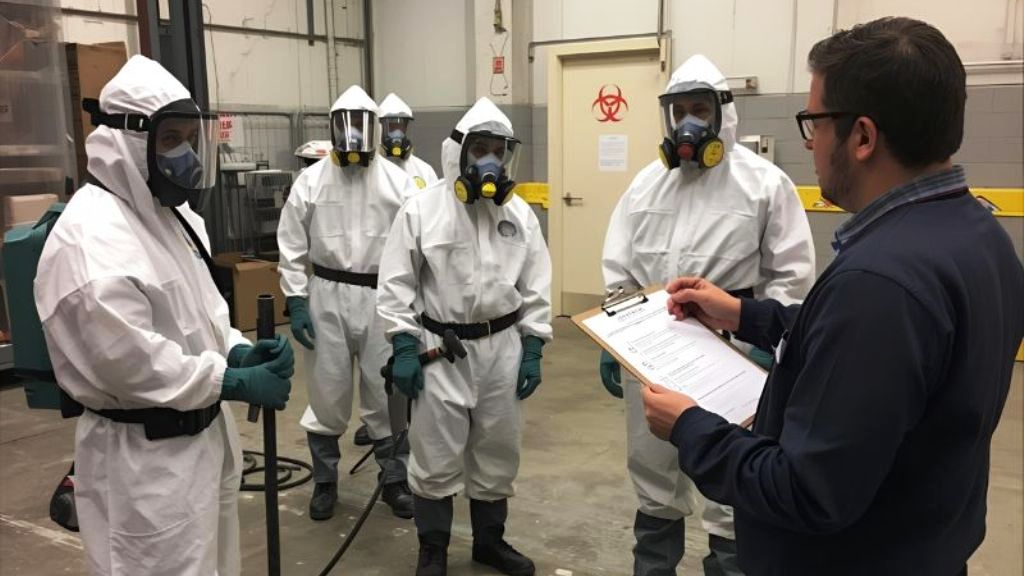
Only after both of those steps are complete should you contact a certified remediation company. When you do, choose an IICRC-certified specialist who understands insurance billing protocols specifically, since the documentation they generate during the job becomes part of your claim file alongside your own photographs.
Documenting Structural Biohazard Damage: What Adjusters Actually Need to See
This is where most homeowners genuinely don’t know what they’re looking for, because the contamination that matters most to your claim is frequently invisible.
Biological fluid doesn’t stay where it lands. On porous materials — carpet, untreated wood, drywall, grout — it moves through capillary action within minutes, penetrating far below what’s visible on the surface. This matters enormously for your claim because insurance adjusters distinguish between surface cleaning, which is relatively inexpensive, and structural remediation involving material removal, which costs significantly more. If your documentation only shows the visible surface stain and doesn’t establish that contamination reached the subfloor or wall cavity, the adjuster has grounds to approve only the cheaper category of work.
Documenting structural biohazard damage properly means capturing evidence of migration, not just the visible spill. If carpet is being removed because fluid reached the padding and subfloor, photograph the underside of the carpet and the padding itself once pulled back, showing the saturation pattern. If drywall requires cutting back beyond the visible stain line — the IICRC S540 Standard for Trauma and Crime Scene Cleanup generally calls for removal at least 12 inches past visible saturation — document the reasoning with photos showing why the cut line was set where it was, not just the finished removal.
A qualified remediation company will typically use moisture meters and, in decomposition cases, UV inspection to map the true boundary of contamination before removal begins. Ask for this documentation specifically. A written scope of work explaining why specific materials required removal, backed by photographic evidence of the actual penetration pattern, is what turns a disputed claim into an approved one.
Collecting the Public Records That Anchor Your Claim
Your insurance claim doesn’t exist in isolation — it needs to be anchored to official records that establish what actually happened, when, and under what circumstances.
The police incident or case report number is the single most important piece of documentation you can obtain, and it should be your first call after any immediate safety concerns are addressed. Ask the responding officer for this number before they leave the scene if at all possible; if you miss that window, contact the responding agency’s non-emergency line the same day and request it. Every insurance adjuster handling a biohazard insurance claim connected to a crime, a suicide, or a suspicious death will ask for this number, and a claim without it moves noticeably slower.
For unattended death situations specifically, insurance adjuster proof for unattended death clean up claims typically requires documentation from the medical examiner or coroner’s office confirming the date of death was established, since this detail matters directly to coverage. Many policies distinguish between contamination resulting from a sudden, recent event and contamination that developed gradually over an extended, undiscovered period — and the medical examiner’s timeline is what determines which category your claim falls into. Request this documentation in writing, and don’t assume it will simply be forwarded to your insurer automatically; following up directly protects your timeline.
Keep copies of every document — the police report, medical examiner correspondence, and any code enforcement or health department notices connected to the property — in a single organized file. Adjusters process complete, organized claims faster than ones requiring repeated follow-up requests for missing pieces.
Trauma Scene Photography for Insurance Adjusters: Getting the Technique Right
Not all photographic evidence carries equal weight, and there’s a real difference between photos that support a claim and photos that just document that something bad happened.
Trauma scene photography for insurance adjusters should include both wide establishing shots and close, detailed images, taken systematically rather than randomly. Photograph each room from multiple angles before anything is disturbed. Include a visible reference point — a doorframe, a piece of furniture — in wide shots so the adjuster can orient themselves within the space. For close-up shots of contamination, include something for scale wherever possible, since size and extent matter directly to the cost of remediation.
Timestamp your photographs if your device doesn’t do this automatically, and avoid editing or cropping images before submitting them, since unedited, metadata-intact photos carry more evidentiary weight than images that appear to have been altered. If you’re photographing before the scene has been officially released by law enforcement, confirm with the responding officer that documentation is permitted — in most cases it is, but confirming avoids any appearance of interfering with an active investigation.
How Line-Item Estimating Protects You From an Underpaid Claim
This is the part of the process most homeowners never see, but it directly determines how much of your remediation bill actually gets covered.
Insurance adjusters at major carriers evaluate claims against Xactimate, the industry-standard estimating software, which prices remediation work using specific line-item codes rather than a single lump-sum figure. A remediation invoice that simply reads “biohazard cleanup — $9,000” gives an adjuster nothing to verify and every incentive to negotiate it down. A properly itemized estimate breaks the same job into distinct, defensible categories: labor hours, PPE surcharges required under OSHA’s Bloodborne Pathogens Standard, biohazard waste disposal fees referenced against a signed waste manifest, structural material removal, odor remediation equipment deployment, and post-remediation ATP verification testing confirming the space meets a safe biological threshold.
When you’re vetting a remediation company, ask specifically whether they generate Xactimate-format estimates with these discrete line items. A company that can’t, or that only provides flat-fee pricing, puts your claim at a structural disadvantage before the adjuster even reviews it — not because the work itself was inferior, but because there’s nothing in the paperwork for the adjuster to actually approve against.
BioRecoveryPro connects property owners with IICRC-certified specialists experienced in insurance documentation and line-item billing, matching you with a contractor who understands exactly what your adjuster needs to see — available 24/7 across all 50 states.
Final Thoughts
Biohazard insurance claim documentation isn’t complicated once you know the sequence: photograph everything before cleanup begins, get your incident number and medical examiner documentation early, understand how structural contamination gets mapped and justified to an adjuster, and insist on an itemized estimate rather than a flat number. Every one of these steps takes minutes to do correctly and can mean thousands of dollars in the difference between a claim that gets approved smoothly and one that gets fought over for weeks.
The property owners who navigate this well aren’t the ones who got lucky with a generous adjuster — they’re the ones who built a documented, defensible case file before anyone touched the scene.